AmeriVet Weekly Muni Snapshot


|
Municipal New Issuance: This past week, the negotiated calendar had a total volume of approximately $11.28 billion with the largest deals being the $1.61 billion Trustees of the California State University Systemwide Revenue Bonds issuance which also issued a series of $113 million in taxable bonds. Notably, AmeriVet served as a Co-Manager for CSU on both transactions. The Washington Metropolitan Area Transit Authority issued $653 million and The Spring Hill Independent School District issued $598 million. |
|
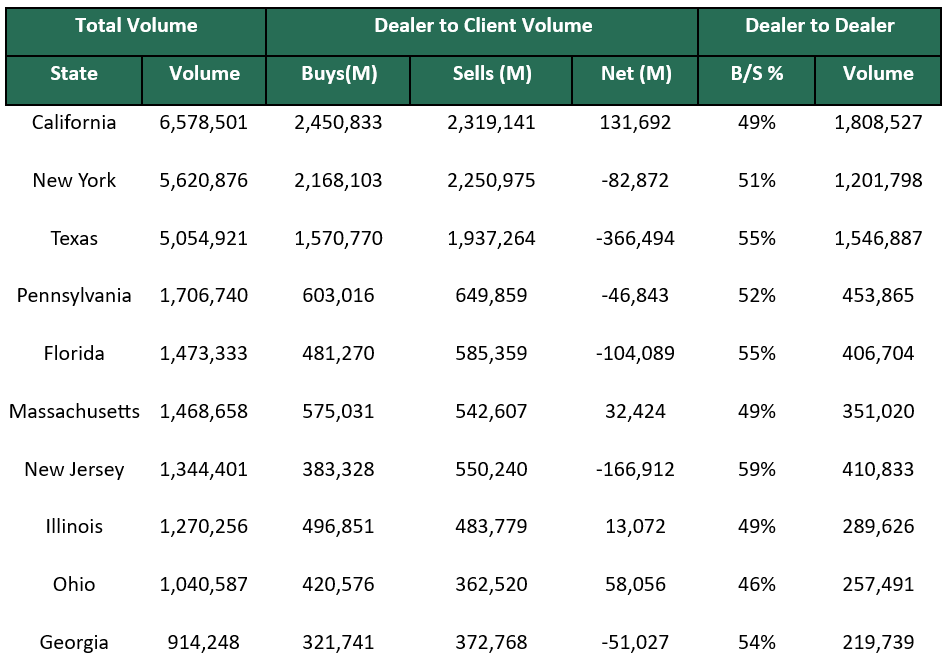
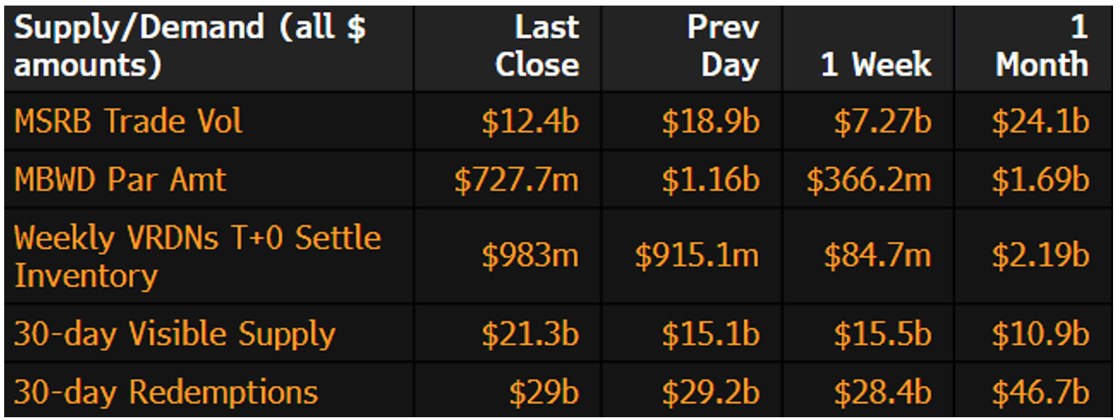
Municipal Secondary Trading: Secondary trading volume totaled to just over $41.36 billion with 52% of secondary trading being dealer sells. According to Bloomberg, clients put roughly $5.46 billion up for the bid, a notable increase from the prior week’s total of $2.81 billion. |
 |
|
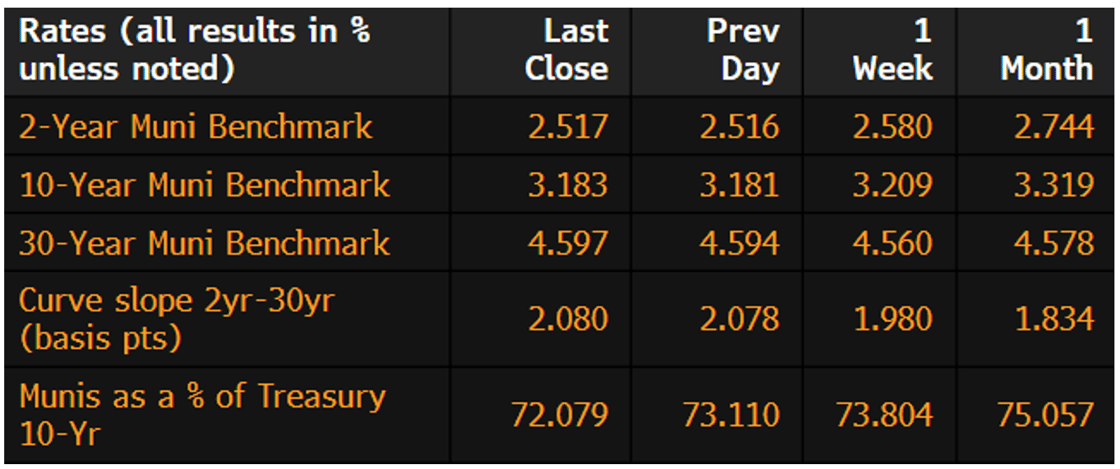
Municipal Spreads: Munis returns were mixed over the past week with the 1–10 year range seeing an average bump of about 5.2 basis points while the rest of the curve saw cuts of about 2.4 basis points, with the majority of the movement being in the earlier part of the week. With yields being mixed, munis did outperform Treasuries with the 10-year muni-to-Treasury ratio now yielding 72.07%, compared to 73.80% a week ago. We continue to see the muni curve steepen with the curve steepening by 9.8 basis points to end the week at 208 basis points. At the start of the year, the curve was at 105 basis points. |
 |
|
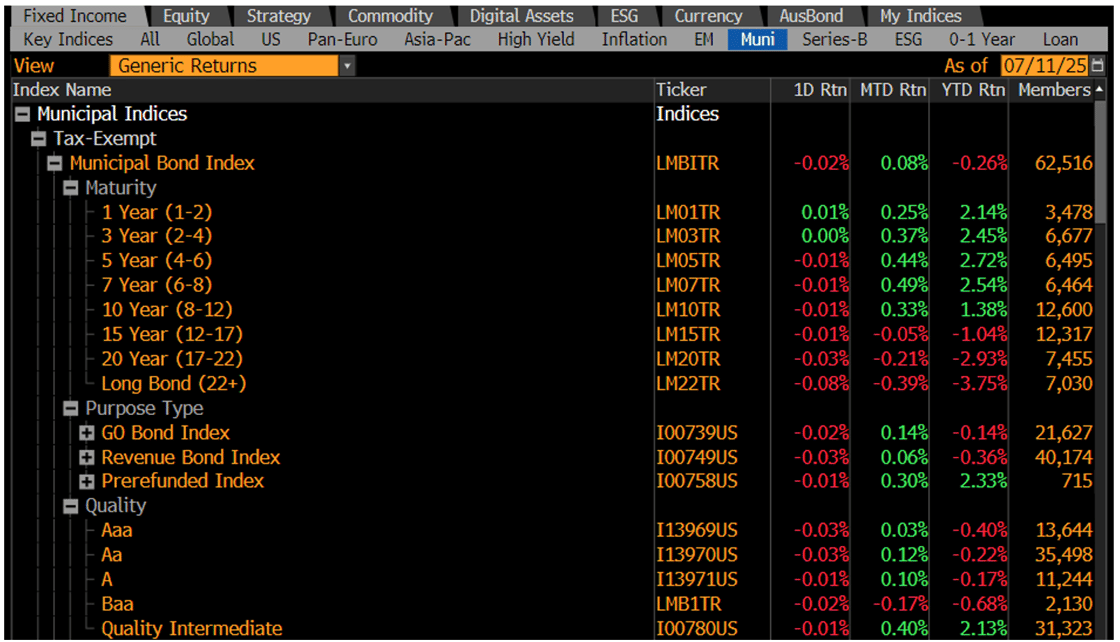
According to LSEG Lipper Global US Fund Flows data, muni bond funds added $432 million to their funds this past week which follows the prior week’s inflow of $958.2 million and marks 11th straight weeks of inflows. We continue to see investors flow into muni funds despite muni being down by .24% for the year. With the front end seeing bumps this past week, munis were able to move into positive territory for the month with month-to-date returns being .08%. The front end of the curve is currently up at 29%, while the long end (22+) continues to struggle with a loss of about .39%, bringing year-to-date losses in the long end to 3.68%. We are in an interesting pocket of time as since the start of the year, the front end has seen the best returns with the front end, seeing gains by an average of about 289 basis points. However, 10-year munis are seeing a modest loss of 7.8 basis points while the long end is down by about 370 basis points. Now that the “One Big Beautiful Bill” has passed and the tax-exemption of munis is intact, coupled with the Fed cutting rates in the fourth quarter, we could see a potential rally in the long end later this year. |
 |
|
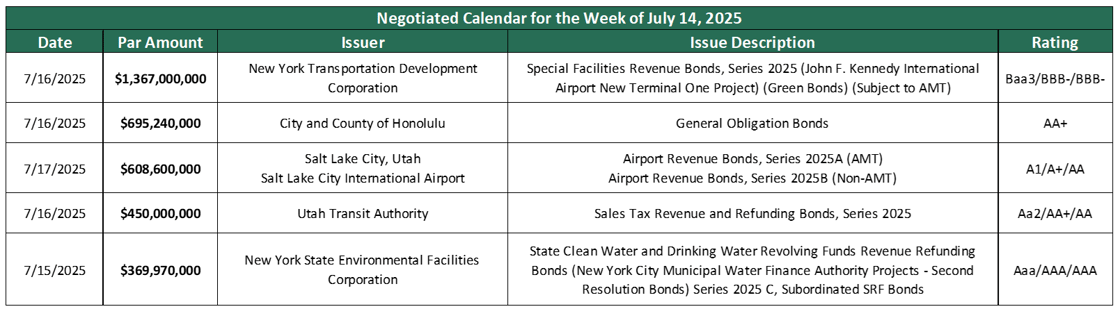
Municipal Supply: The negotiated calendar for the week will have an expected volume of approximately $8.25 billion with the largest deal of the week being the $1.36 billion New York Transportation Development Corporation for the JFK airport. The next largest deal of the week will be the City and County of Honolulu GO Bonds issuance which is expected to issue $695 million. Salt Lake City, Utah plans to sell $608 million in Airport Revenue Bonds. Have a great week! |
 |
 |