AmeriVet Securities 2025 Municipal Review


|
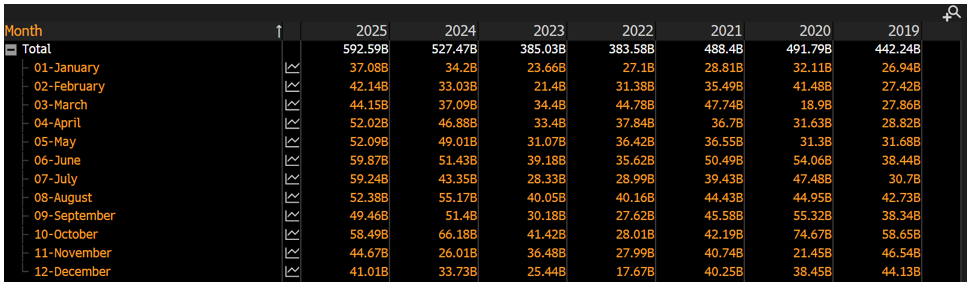
Municipal New Issuance: New Issuance for 2025 totaled to just over $592 billion, surpassing the 2024’s record year of $527 billion. June saw the largest issuance of $59.8 billion for the year, while January saw the lowest issuance of $37 billion. California saw the largest issuance of $90.8 billion followed by Texas which issued $83.5 billion, New York followed next by issuing $77.3 billion. Taxable issuance for the year totaled to $39.47 billion, just over 2024’s total issuance of $39.4 billion. New York issued the most in taxable bonds with $7.86 billion, California issued the next largest of $5.23 billion, followed by Texas with $4.51 billion. |
 |
|
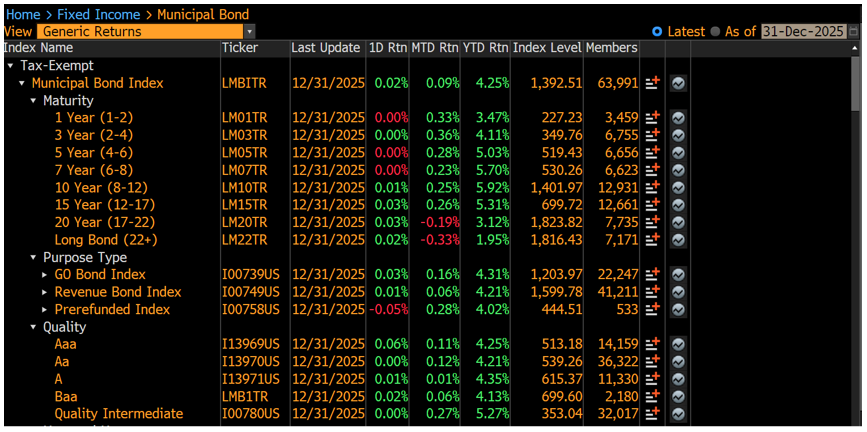
Municipal Year-to-Date: Muni returns for the year totaled to 4.25%, besting 2024 returns of 1.05%. The 10-year range saw the largest gains for the year with 5.92% returns. The long-end saw the smallest gains of the year with 1.95% in total gains. New Hampshire saw the largest returns for the year with a return of 6.27% while Arkansas saw the lowest returns of 2.95%. |
 |
|
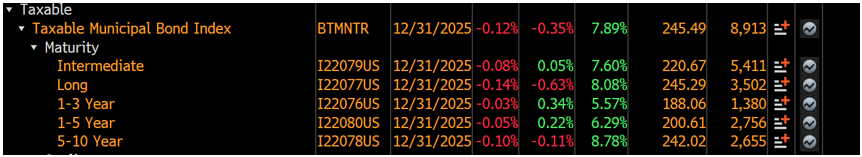
Taxable bonds saw some strong returns of 7.89%, beating out last year’s returns of 1.57%. The 5–10-year range saw the largest returns of 8.78%, while the 1–3-year range saw the lowest returns of 5.57%. |
 |
|
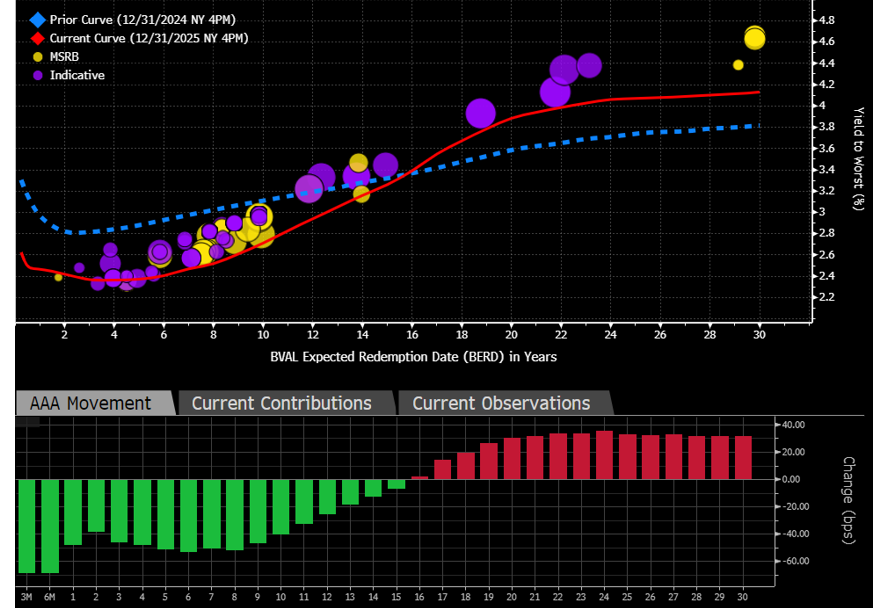
With the muni curve steepening this past year, we did see yields from 2026-2040 fall while the maturities 2041-2055 rise. With yields seeing bumps of 40-53 basis points in the 2026-2035 range, the 2036-2037 maturities saw yields bump by 25-32 basis points, while the 2038-2040 maturities saw bumps of 6-18 basis points. The 2041-2043 range saw cuts of 1-20 basis points while the 2044-2055 maturities saw cuts of 26-35 basis points. These factors have pushed the yield curve to steepen by 68.8 basis points. |
 |
|
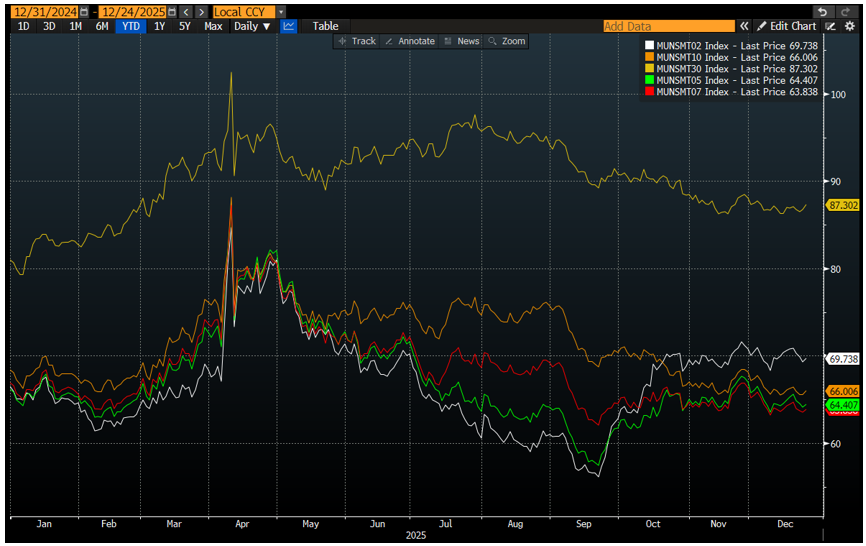
Although muni were in the green for the year, muni performance compared to Treasuries were mixed as 5-year, 7-year, and 10-year maturities outperformed Treasuries as the 5-year muni-to-Treasury ratio started the year off at 66.21% and ended the year at 64.40%. The 7-year muni-to-Treasury ratio started the year at 68.41% and ended the year at 63.83% while the 10-year muni-to-Treasury ratio started at 68.41% and ended the year at 66%. The 2-year and 30-year ratios saw munis underperform Treasuries the most as the 2-year ratio saw the ratio started the year at 66.46% and ended the year at 69.73%. The 30-year ratio saw similar underperformance for munis as we witnessed the muni-to-Treasury ratio begin at 80.99% during the start of the year to finish the year at 87.30%. |
 |
|
2026 Issuance: AmeriVet is expecting to see over $610 billion of municipal issuance, surpassing the record issuance of $592 billion last year. We should expect record issuance this year driven by increases in infrastructure spending nationwide as inflation continues to remain elevated. National infrastructure spending and a favorable interest rate environment should ignite issuance across the country as the Fed continues cutting rates in 2026. Investor demand should continue to remain high as reinvestment will play a strong role in muni demand as roughly $701 billion in principal and coupon payments are due in 2026 which will outpace expected issuance. |
|
2026 Supply: We should continue to see a positive outlook for munis as yields continue to look attractive for investors as they will continue to take advantage of the higher yields before further rate cuts. Higher yields coupled with favorable supply and demand should drive investment demand even more than last year, eventually driving yields lower. We should expect to see overall credit quality to remain stable as state and local governments continue establish and collect strong tax revenues as well as strong rainy-day funds from Covid-19 relief funds. |