AmeriVet Weekly Muni Snapshot


|
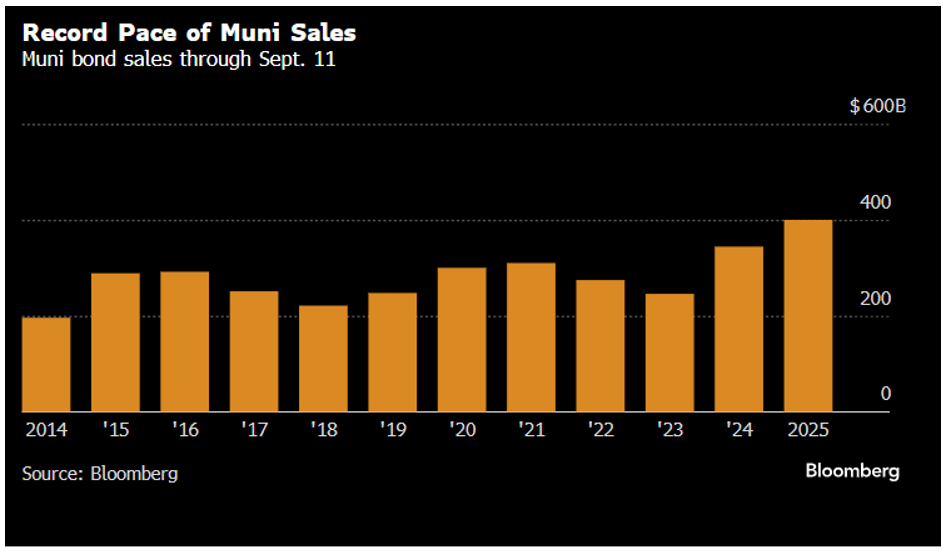
Municipal New Issuance: This past week, the negotiated calendar totaled to just over $9.9 billion, with the largest deal of the week being the $1.9 billion Dallas-Fort Worth, Texas International Airport. The next largest deal of the week was the $965 Black Belt Gas District issue. The City of Atlanta Department of Aviation issued $1 billion. AmeriVet participated in one issue this past week as a Selling Group Member for the $37 million Connecticut Housing Finance Authority. The new issue market surpassed $400 billion this past week which is approximately 17% higher from the same period last year, marking the fastest pace of issuance since 2014 to reach over $400 billion in total issuance. |
 |
|
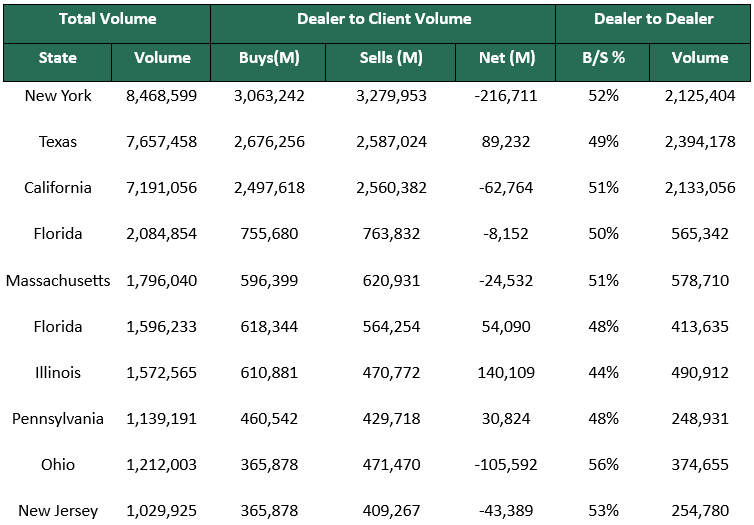
Municipal Secondary Trading: Secondary trading volume totaled just over $51.41 billion, with 51% of secondary trading being dealer sells. According to Bloomberg, clients put roughly $4.58 billion up for the bid, an increase from the prior week’s number of $3.46 billion. |
 |
|
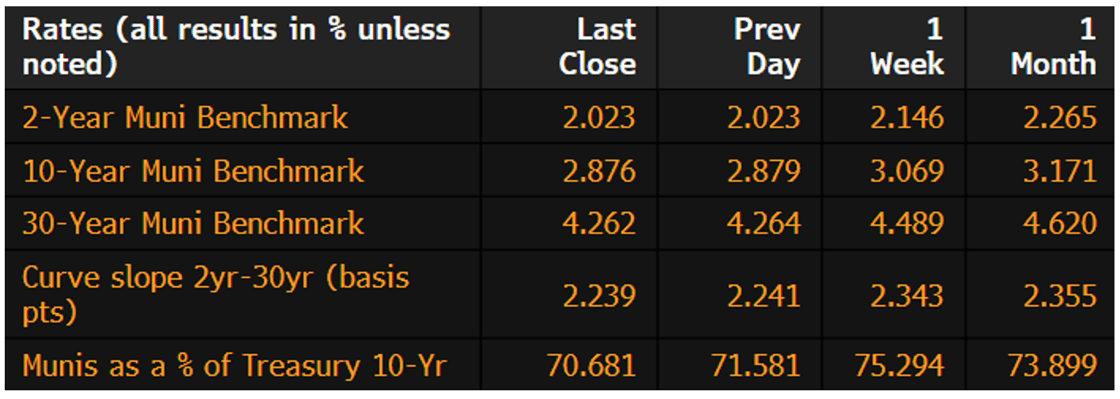
Municipal Spreads: For second week in a row, munis saw a strong rally with yields falling by an average of 18.9 basis points as 10-year notes saw a bump of 19.3 basis points to end the week at 2.87%. With this rally, munis were able to outperform Treasuries as the muni-to-Treasury ratio is now yielding 70.68, compared to 75.29% from the prior week. We did see the muni curve flatten this past week by 10.4 basis points to finish the week at 234 basis points. |
 |
|
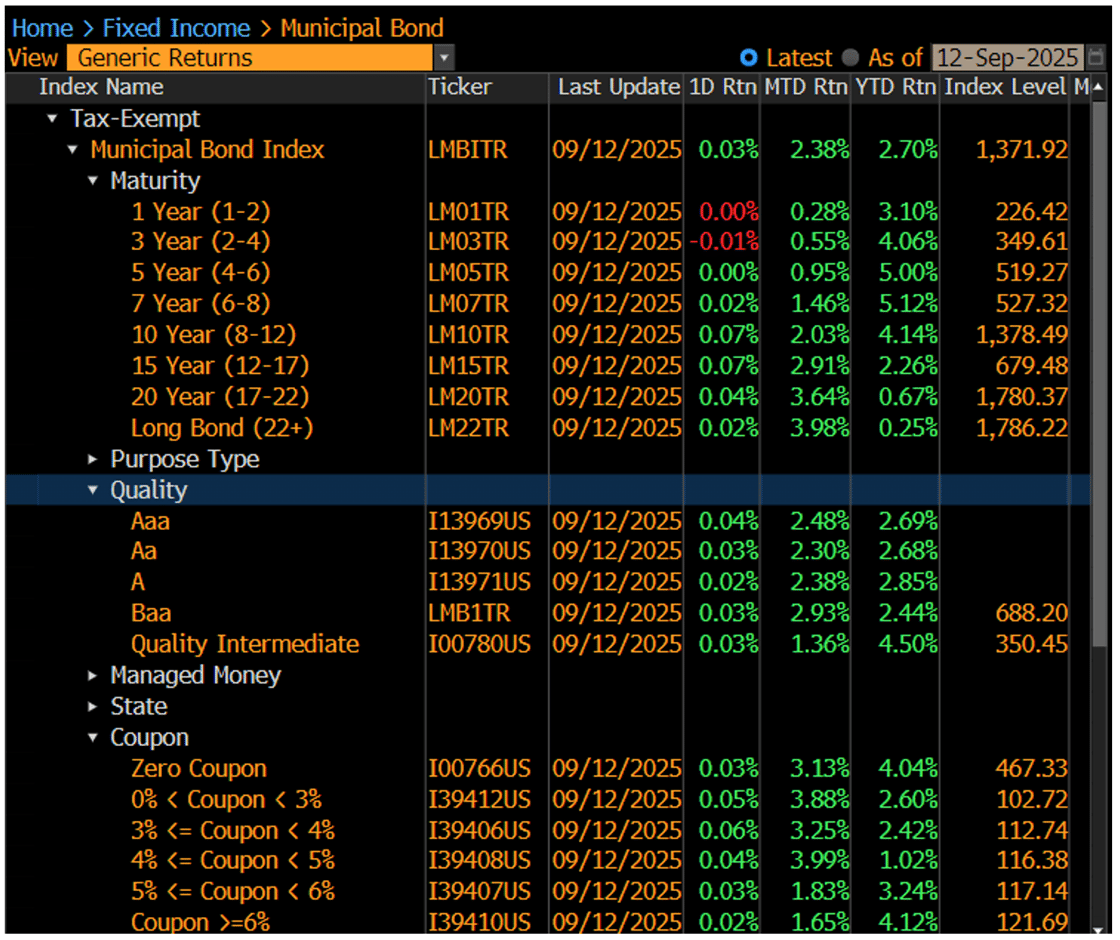
According to LSEG Lipper Global U.S. Fund Flows data, investors added roughly $2.2 billion to muni bond mutual funds this past week. This follows the prior week’s inflow of $672 million. This was the second largest inflow year-to-date with the largest inflow coming in just four weeks ago at $2.33 billion. Munis continued their rally this past week as everyone is focused on this week’s anticipated rate cut, with the largest bumps in the curve being in the long end. The long end of the curve saw bumps of about 22 basis points giving us a month-to-date returns of just under 4%. This was a much needed rally as the long end struggled throughout the year, but now has been pushed back into positive territory. So far this month, muni yields are down about 38 basis points in the long end, with the belly seeing a bump of about 36 basis points while the front end is experiencing a bump of approximately 20 basis points. Currently, month-to-date returns for munis are at 2.38%, which brings year-to-date returns to 2.70%. With CPI and jobless claims coming in hotter then expected, this data has all but solidified a 25 basis point cut later this week and set the stage for potentially two more cuts later this year, which could continue to fuel a rally for the remainder of the year. |
 |
|
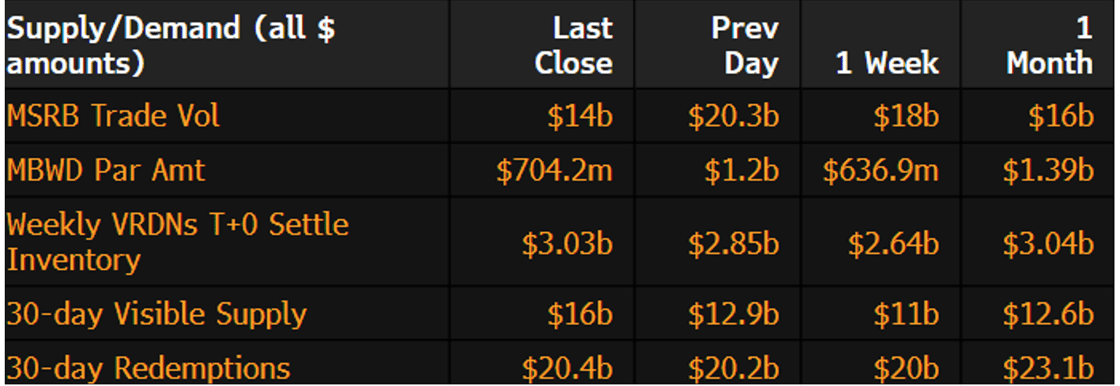
Municipal Supply: Supply for the week will have an expected volume of just over $4.13 billion with the largest deals of the week being the $1 billion Metropolitan Transportation Authority issue which AmeriVet will be participating in the Selling-Group, followed by the City of Houston which plans on issuing $289 million. The Douglas County School District plans on issuing $274 million. AmeriVet will be in three other issues this week as a Selling Group Member for the New York City Housing Development Corporation which will issue $198 million in taxable bonds and $41 million in tax-exempt bonds, the $87 million Minnesota Housing Finance Agency, and the New Hampshire Housing Finance Authority which will issue $70 million in tax-exempt bonds and $30 million in taxable bonds. Have a great week! |
 |