AmeriVet Weekly Muni Snapshot
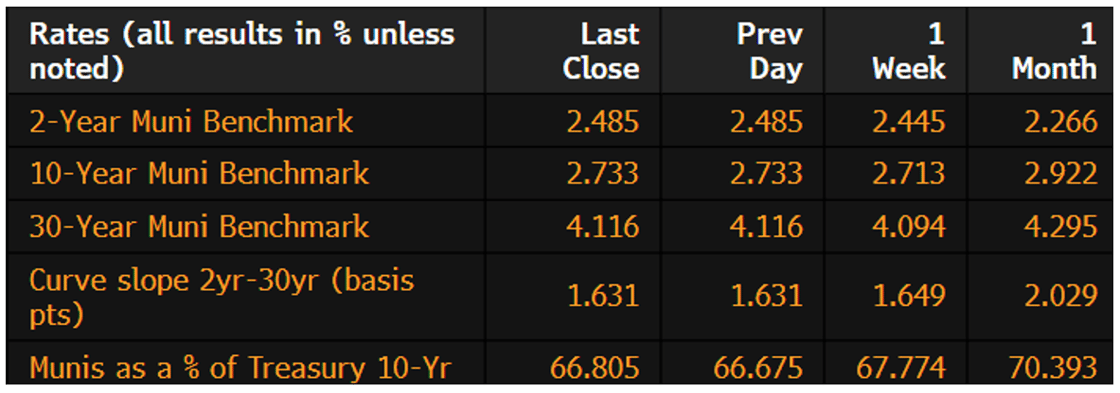
Municipal Spreads: This past week, muni yields rose by an average of about 2.4 basis points, with yields on 10-year notes rising by 2 basis points to end the week and month at 2.73%. With yields rising over the past week, munis did underperform Treasuries with the 10-year muni-to Treasury ratio now yielding 68.80%, compared to 67.77% a week ago. At the start of the month the ratio was at 70.39%. We did see the muni curve flatten by 1.8 basis points to end the week at 163 basis points.
|
 |
According to LSEG Lipper Global U.S. Fund Flows data, investors added roughly $720 million to municipal bond funds last week. This follows the prior week’s inflow of $1.1 billion. Muni funds have added about $4.56 billion for the month of October.
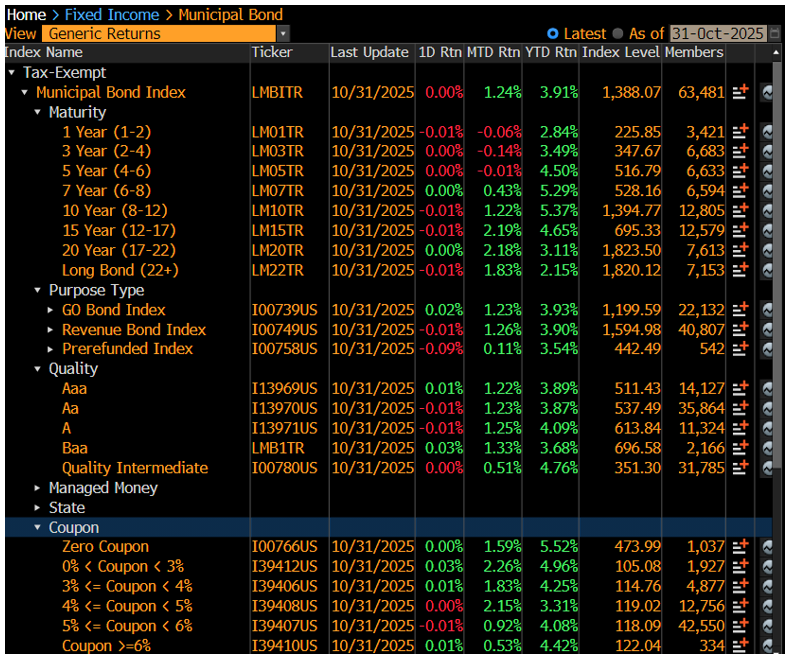
Returns for the month totaled 1.24%, with the 12–17-year range showing the largest returns at 2.19%, while the 1–2-year range showed the largest loss of just .06%. This brings the year-to-date return to 3.91%. In comparison, last year the month of October saw a loss of 1.46% and a modest year-to-date return of .81% by the end of the month.
Muni yields have fallen an average of 8.6 basis points across the curve with the 10–30-year maturity range seeing bumps of 15-17 basis points. Meanwhile, the front end continues to struggle with cuts of about 24 basis points. Munis flattened to about 398 basis points throughout the month. They continued to outperform Treasuries in the 10–30-year ranges, with the 10-year maturity outperforming Treasures by about 3.5 percentage points and the 30-year maturity by 2.5 percentage points. The 2–5-year maturity range continues to underperform, with the 2-year maturity underperforming Treasuries by 6 percentage points and the 5-year maturity range by 3.3 percentage points.
|
 |
In the past 10 years, November has only seen 2 negative performances, being in 2016 and 2017. With the rate cut last week and a rate cut in December being less certain, November should continue the October momentum as inflows continue to be steady and estimated $42 billion in principal and interest in redemptions coupled should increase demand for munis.
|