AmeriVet Weekly Muni Snapshot


|
Municipal New Issuance: For the third week of December, the negotiated calendar totaled to over $8.13 billion with the largest deal of the week being the New York City Transitional Finance Authority’s $1.8 billion Future Tax Secured issuance which AmeriVet participated in the Selling-Group. The Authority also issued $167 million of Future Tax Secured Taxable bonds. The Kentucky Public Energy Authority issued $748 million. Additionally, The Ohio State University issued $500 million. |
|
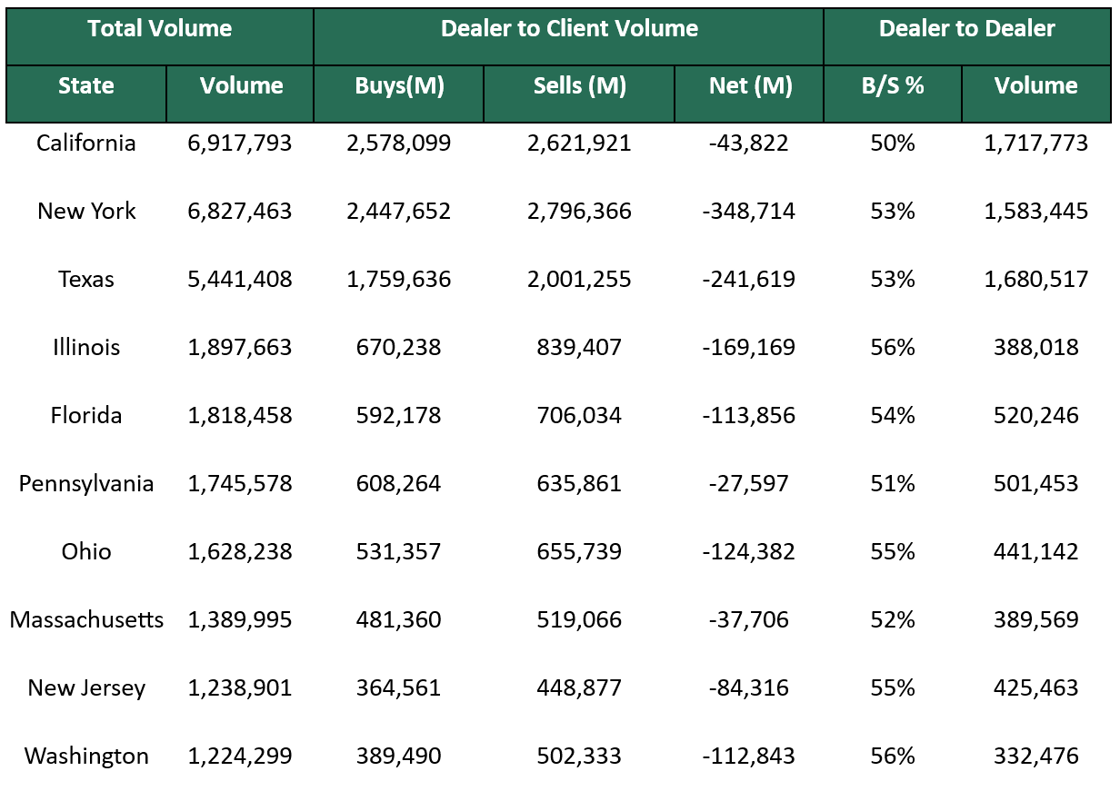
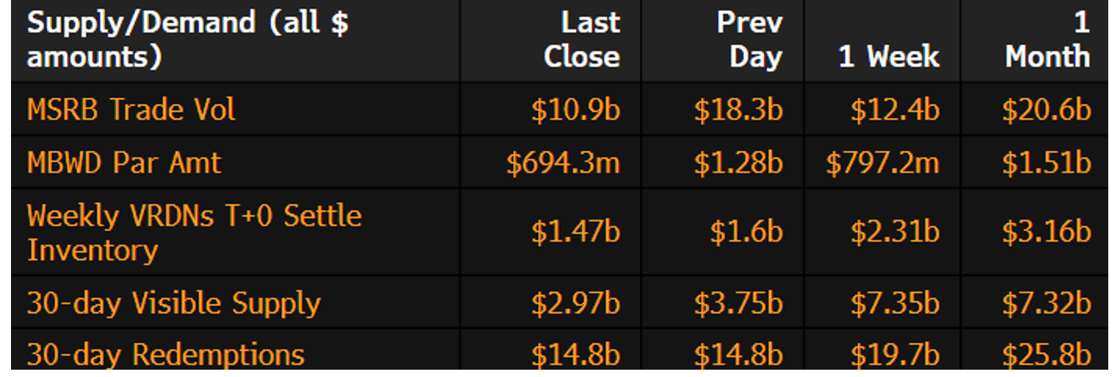
Municipal Secondary Trading: Secondary trading volume totaled to approximately $47.17 billion with 53% of secondary trading being dealer sells. According to Bloomberg {MBWDPAR Index}, clients put roughly $6.21 billion up for the bid, an increase from the prior week’s number of $5.81 billion. |
 |
|
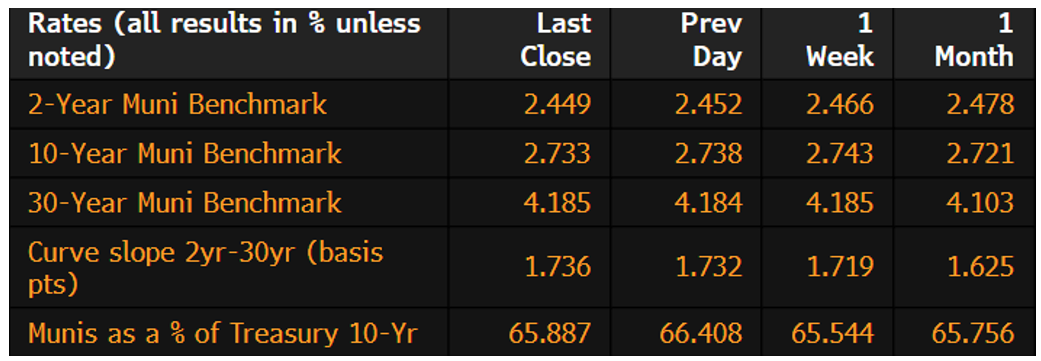
Municipal Spreads: This past week, munis yields were relatively unchanged for with 10-year notes falling by 1 basis points to end the week at 2.73%. With yields being unchanged for the week, munis did underperform Treasuries as the 10-year muni-to-Treasury ratio is now yielding 65.88% compared to 65.54% from the prior week. We did see the muni curve steepen by 1.7 basis points to end the week at 173 basis points. |
 |
|
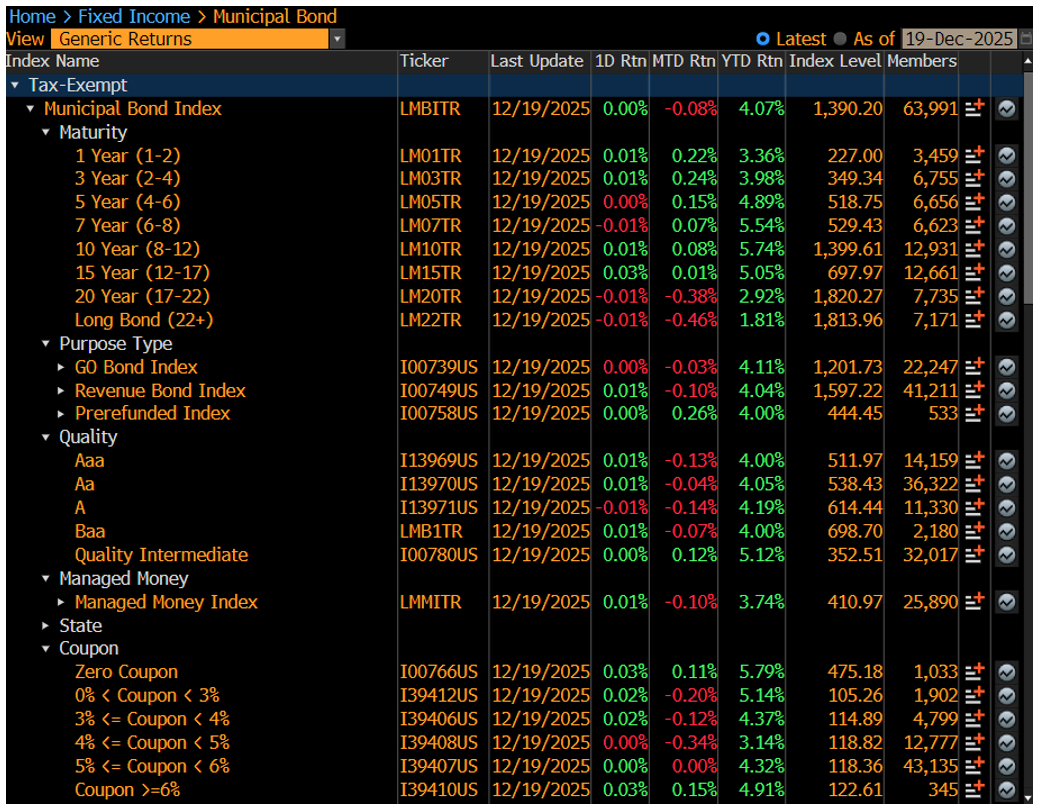
According to LSEG Lipper Global US Fund Flows data, investors added $400 million to muni bond funds this past week, succeeding the prior week’s inflow of $16 million. Prior to the release of the positive inflation data, munis were down a basis points for the week. However, when the CPI data was released last week, munis saw a one basis point bump. Despite this bump, munis are still down for the month with just two weeks left in the year. The 1-4 year range are seeing the largest gains of .22% to .24% for the month while the long end has struggled this month being down .46%. Currently, munis are down slightly for the month as returns for the month are at .08% with year-to-date returns at 4.07%. With the strong CPI data, we could see the Fed take a pause in cutting rates in January but that would largely depend upon December’s CPI report which will be released during the 2nd week of January. |
 |
|
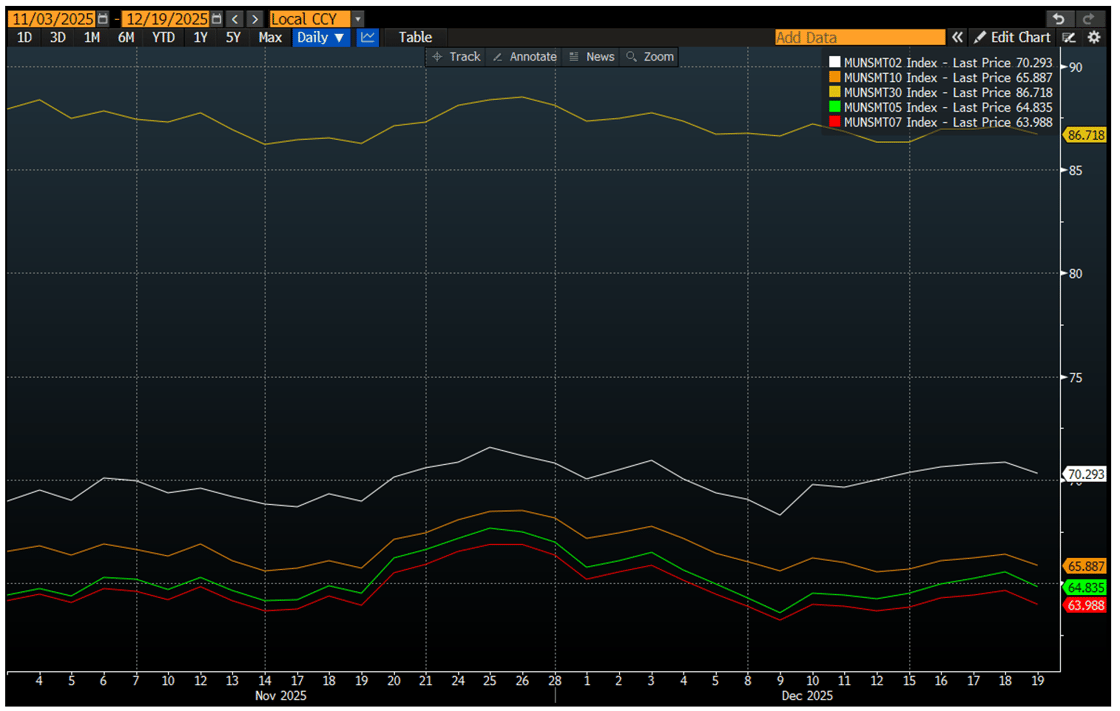
With yields being unchanged for the week, munis have outperformed Treasures for the month as the 2-year ratio on Friday was at 70.29%. whereas at the start of the month the 2-year ratio was at 70.81%. The 5-year ratio at the start of the month was at 66.97% compared to 64.83% on Friday while the 7-year ratio was at 66.34% at the start of the month and is now yielding 63.98%. The 10-year ratio at the start of the month was at 68.17% compared to 65.88% on Friday, and finally, the 30-year ratio was at 88.08% at the start of the month and on Friday the ratio was at 86.71%. With just 7 trading days left, we shouldn’t expect too much change in ratios. |
 |
|
Municipal Supply: With Christmas Holiday this week, issuers will take a pause from issuing and will be done issuing for the year. Have a great week! |
 |