AmeriVet Weekly Muni Snapshot
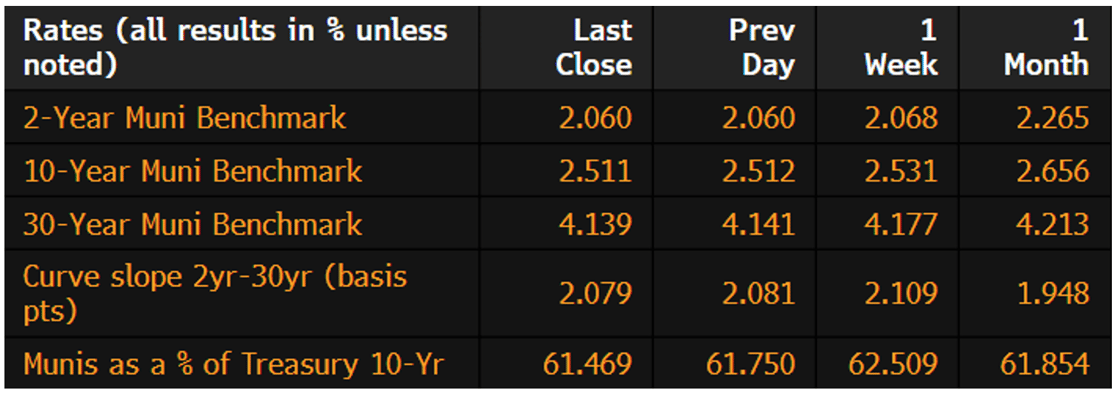
Municipal Spreads: Muni yields continue to fall this past week as yields fell by an average of 2.4 basis points across the curve with yields on the 10-year notes falling by 2 basis points to finish the week at 2.51%. With yields falling, munis did outperform Treasuries once again this week as the 10-year muni-to-Treasury ratio is now yielding 61.47% compared to 62.51% from the prior week. At the start of the year, the 10-year muni-to-Treasury ratio was at 65.43%. We did see the muni curve flatten this past week by 3 basis points to end the week at 208 basis points.
|
 |
According to LSEG Lipper Global U.S. Fund Flows data, muni bond funds continue to see inflows as investors added $1.3 billion to muni bonds funds. This follows the prior week’s inflow of $1.57 billion and marks the thirteenth straight week of inflows. This is also the sixth time in seven weeks in which we had over $1 billion of inflows.
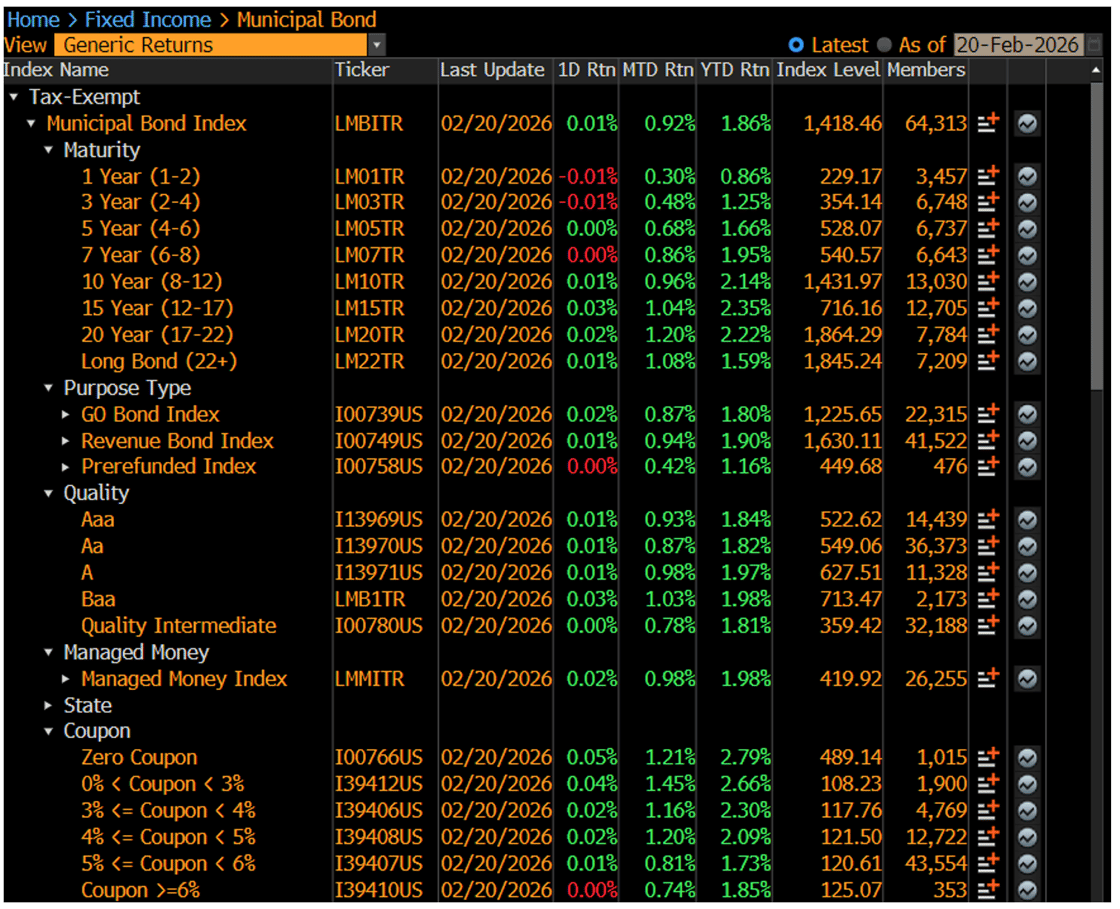
Munis continue their solid month with gains for the month now at .92%, pushing year-to-date returns to 1.86%. This past week, the 2039-2056 maturities saw bumps of 3-3.8 basis points, while the 2032-2038 saw bumps of 1-2.7 basis points. The 2027-20231 maturity range saw a modest gains of just 1 basis points. With bumps this past week coupled with Treasuries pulling back sharply, munis were able to outperform Treasuries across the curve as this move is driven by strong tax-exempt demand as seen by recent inflows and reinvestment demand continuing to outdrive supply. Treasuries faced modest pressure from macro data and rate volatility, creating a divergence in performance. As a result, munis finished the week firmer on a relative basis despite broader rate uncertainty as negative sentiment around tariffs at the end of the week drove Treasuries higher.
|
 |