AmeriVet Weekly Muni Snapshot
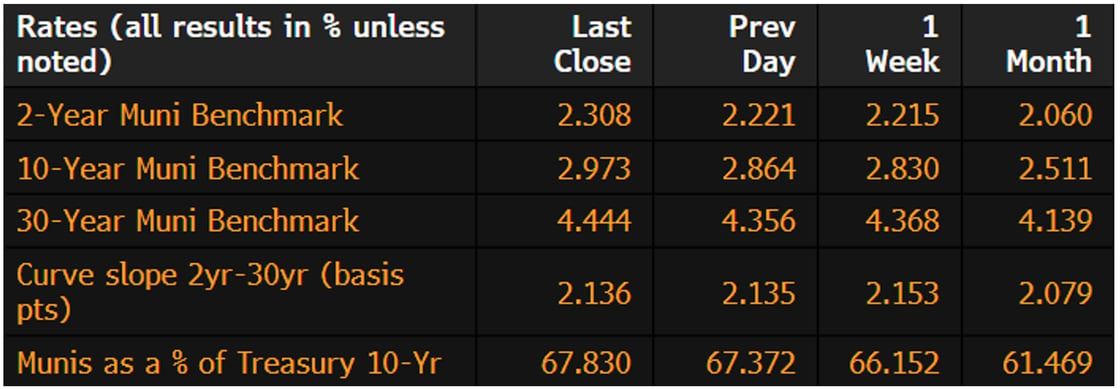
Municipal Spreads: Muni yields continue to rise this month as yields rose by an average of 9.7 basis points across the curve with yields on 10-year notes rising by 14.3 basis points to end the week at 2.97%. With yields rising, munis did underperform Treasuries with the 10-year muni-to-Treasury ratio now yielding 67.83%, compared to 66.15% a week ago. Just one month ago, the ratio was at 61.47%. We did see the muni curve steepen this past week by 1.7 basis points to end the week at 214 basis points.
|
 |
According to LSEG Lipper Global U.S. Fund Flows data, muni bond funds continue to experience strong inflows despite global volatility and uncertainty in the markets due to the war in Iran with muni bond funds seeing investors add $108 million to muni bonds funds. This follows the prior week’s inflow of $612 million and marks the seventeenth straight weeks of inflows.
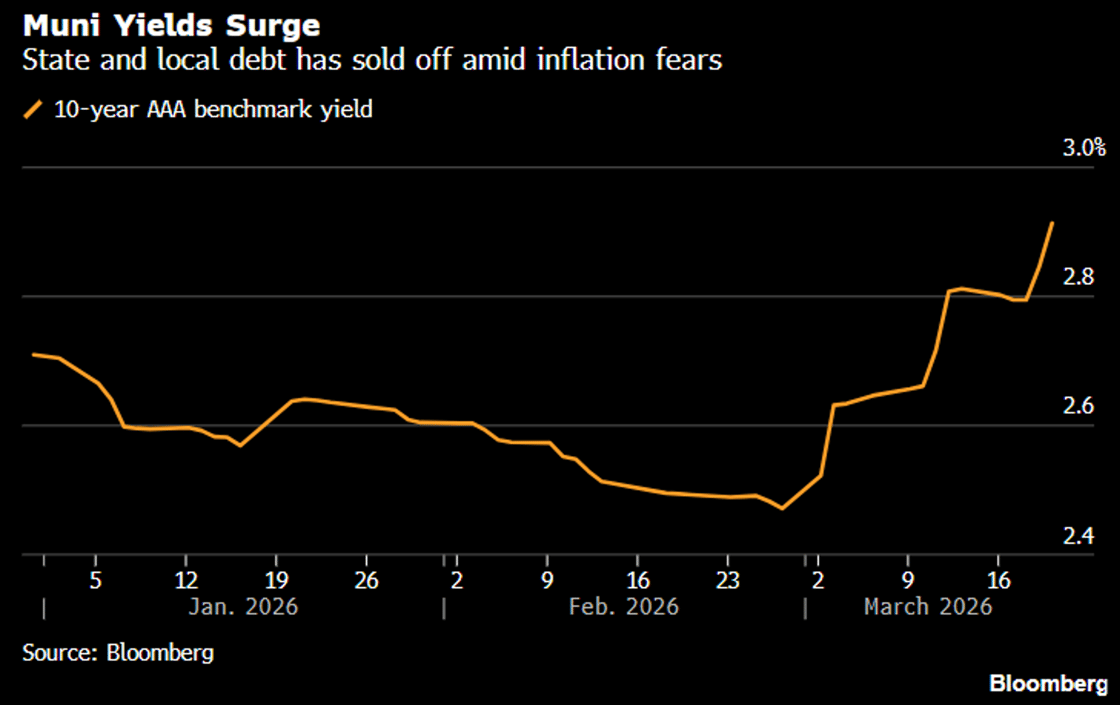
Munis continued their weakness this week with the belly of the curve seeing the largest cuts of 14 basis points. The front end experienced cuts of 9 basis points while the long end saw 6-7 basis point cuts this past week. This brings the month-to-date returns to -1.92% and year-to-date returns to .23%. The sell-off this past week was driven largely by macro forces than credit as rates backed up alongside Treasuries which is also attributed to inflation concerns, but mostly geopolitical tensions. With the Fed keeping rates unchanged, traders and investors are in a “holding pattern” as signs of future cuts this year dwindle. We are in interesting times as the market must now balance these robust technicals against a backdrop of geopolitical tension in the Middle East and the nomination of Kevin Warsh, whose hawkish reputation is already being weighed by participants. We have seen yields on the 10-year AAA benchmark surge from 2.42% at the start of the month to 2.95% on Friday. Overall, munis have cheapened this past week with ratios widening, as the market continues to navigate macro-driven headwinds despite still-solid underlying fundamentals.
|
 |